Daytona Beach is not typically grouped with Florida’s largest housing markets. The metro remains relatively small by national standards, with fewer than 750,000 residents, and its economy has historically been driven by tourism and services.
In recent years, however, Daytona Beach has become a more meaningful source of new-home activity: the market benefited from Florida’s pandemic-era migration surge as households sought lower-cost alternatives to some of the state’s larger coastal metros. Builders responded with new communities across the region, helping expand a housing market that had traditionally been more closely associated with retirees than with large-scale home building.
Florida’s housing environment looks different today. Migration has slowed from pandemic highs, mortgage rates remain elevated, and affordability pressures continue to weigh on demand. Daytona Beach has experienced many of the same challenges, with builders pulling back from the rapid pace of construction seen during the post-pandemic expansion.
Even so, several fundamentals continue to stand out related to aerospace and population growth.
Construction Activity Remains Elevated
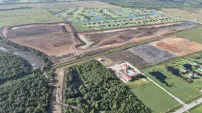
Housing activity has moderated from recent highs, but it remains well above pre-pandemic levels. Annualized housing starts are near 2,700 homes, even as construction has slowed as builders adjust to softer demand conditions. That said, Daytona Beach’s new-home closings have continued to hold up comparatively well.
The result is a market that looks considerably different than it did just a few years ago. Daytona Beach continues to be a bright spot as the Sunshine State struggles, benefiting from population gains, migration, and a meaningful level of new-home construction.
The insights in this article were taken from more in-depth research reports published in Zonda’s National Outlook.