Housing demand is being reshaped by forces that extend far beyond interest rates. Aging consumers, changing household structures, affordability pressures, and evolving lifestyle expectations are creating new challenges and opportunities for builders and developers.
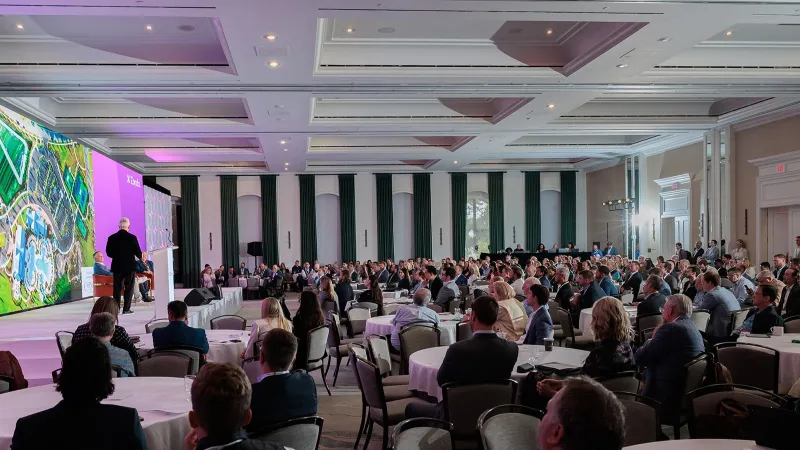
At Future Place 2026, speakers repeatedly returned to a common theme: buyers are not simply shopping for homes, they are shopping for places, experiences, and communities that support the way they want to live.
Across presentations from master-planned community experts, developers, and demographic researchers, one message emerged clearly: the next generation of successful communities will be defined less by the quantity of their amenities and more by their ability to create identity, connection, and long-term value. Below are six key takeaways from the first day:
Buyers Are Adjusting to a Challenging Market
The market remains difficult. Builders continue to contend with elevated mortgage rates, cautious consumers, and margin pressure from incentives and pricing adjustments. Yet speakers suggested the industry may be entering a new phase in which buyers are becoming more willing to accept market realities.
According to data presented by Zonda’s Mollie Carmichael, builder sentiment in August was 78% negative and 22% positive. At the same time, mortgage rates stood at 7.19% for a 30-year fixed loan and 6.81% for a 15-year loan. Despite those headwinds, many consumers have stopped waiting for conditions to return to previous levels.
While some are accepting conditions, that does not mean affordability concerns have disappeared. First-time buyers remain highly payment-sensitive, while move-up buyers need compelling reasons to choose a new home over staying put. But speakers indicated that builders who focus solely on rate buydowns may be missing a larger opportunity.
“Monthly payment is everything” for first-time buyers, Carmichael noted, yet today’s consumers are also looking for financial flexibility, resilience, convenience, personalization, and meaningful lifestyle benefits.
She reminded attendees, “It’s how you make them feel, the human factor.”
Demographics Are Becoming More Important Than Mortgage Rates
While much of the industry’s attention remains focused on financing conditions, several sessions argued that demographic changes could have an even greater long-term impact on housing demand.
By 2030, deaths are projected to outnumber births in the United States, making net immigration the primary driver of population growth. Marriage is occurring later, parenthood is happening later, and child-free households are becoming more common. By 2035, the nation is expected to have 11 million residents age 85 and older.
Meanwhile, retirees and solo-root buyers accounted for 56% of second-quarter 2026 shoppers, underscoring how dramatically the buyer pool is evolving.
Generational researcher Kim Lear’s presentation on generational trends highlighted the growing importance of longevity, wellness, and multigenerational living. She noted that “everything is intergenerational,” pointing to a housing market increasingly shaped by overlapping life stages rather than traditional demographic categories.
For builders, the implications are significant. Universal design features such as zero-step entries, wider doorways, single-story layouts, and mobility-friendly pathways are moving closer to the mainstream. Multigenerational floor plans, flexible spaces, and low-maintenance homes are likely to become important across multiple buyer segments as younger generations also have a say in their parents’ living choices, Lear pointed out.
Master-Planned Communities Continue to Outperform
Zonda’s data also reinforced the continuing strength of the master-planned community model. Master-planned communities remain heavily concentrated in Sun Belt markets, where they continue to generate strong absorption rates. According to Sean Fergus, nine of the top master-planned communities recorded more than 400 starts through the second quarter, with nearly all of the top-performing projects exceeding 300 starts.
“Master plan projects just sell faster,” Fergus said.
The performance extends across multiple buyer segments. Active-adult master-planned communities continue to outperform standalone active-adult developments, while multigenerational neighborhood segmentation was identified as a potential 30% growth opportunity, according to Zonda data. For 2026, Brookfield has led the top MPC developers with 2,007 sales year-to-date.
The advantage, speakers suggested, goes beyond amenities. Successful MPCs should function as ecosystems, combining housing, recreation, social programming, retail, and wellness into a single experience that is difficult to replicate elsewhere.
The Era of Amenity Wars Is Ending
Perhaps the strongest theme of the day was the industry’s growing shift from amenities to identity.
For decades, developers competed by adding larger clubhouses, more elaborate pools, golf courses, and recreational facilities. Future Place speakers argued that these features now represent expectations rather than differentiators.
“Golf, clubhouse, pickleball. These are table stakes, not differentiators,” Carmichael noted during the master-plan outlook discussion. Instead, communities are competing through culture, storytelling, art, wellness, and social connection.
Examples included community murals, resident-created art installations, neighborhood storytelling projects, memory walls, sculpture programs, annual art competitions, and cultural programming designed to foster interaction among residents. Carmichael described these elements as social infrastructure, helping communities create a stronger sense of belonging.
The goal is no longer simply to provide things for residents to do. It is to give residents a reason to identify with a place. She concluded, “Not more amenities. More meaning. More life.”
That idea also resonated with Phillip Huffines, who told the audience, “We focus on the word ‘community’ as more of a verb than a noun,” in a CEO panel on MPC scale and trajectory.
Momentum Still Matters
Even amid evolving consumer preferences, traditional development fundamentals remain critical. A CEO panel featuring Brent Herrington, Casey Tischer, and Huffines repeatedly emphasized the importance of momentum during a community’s launch phase.
Strategies discussed included building interest lists before opening, investing heavily in the first phase of development, creating model villages rather than scattering individual model homes, and ensuring buyers see strong value from the earliest sales.
“Momentum is always important in our business, but it’s most important at the launch of a new community,” said Herrington.
He later added the day’s most practical reminder: “Momentum. Once you have it, it changes everything.”
For builders operating within master-planned communities, that early momentum can affect everything from traffic and buyer confidence to future pricing power and absorption rates, the panel said.
Buyers Are Purchasing Places, Not Homes
The conference’s most enduring takeaway came during a fireside chat with Legends Award winner David O’Reilly, who argued that successful communities are defined by far more than housing.
“The completeness of that environment is what drives quality of life,” O’Reilly said.
He emphasized the importance of employment centers, retail, recreation, housing diversity, and thoughtful development sequencing. Jobs, he noted, drive daytime activity that supports restaurants, shops, and community vitality. Every project requires a unique approach because no two markets are identical.
His most memorable observation captured the broader theme running throughout the sessions: “When people buy into The Woodlands, they’re not buying a home. They’re buying a place,” O’Reilly said.
That statement may best summarize the message of day one. In an era of affordability challenges, demographic shifts, and increasing buyer segmentation, the industry’s next competitive advantage may not come from building a better house. It may come from building a more complete place.